Digital Pension Architecture & e-NPS: How Central Recordkeeping Agencies (CRAs) and UPI Micro-SIPs Transformed Retirement Savings
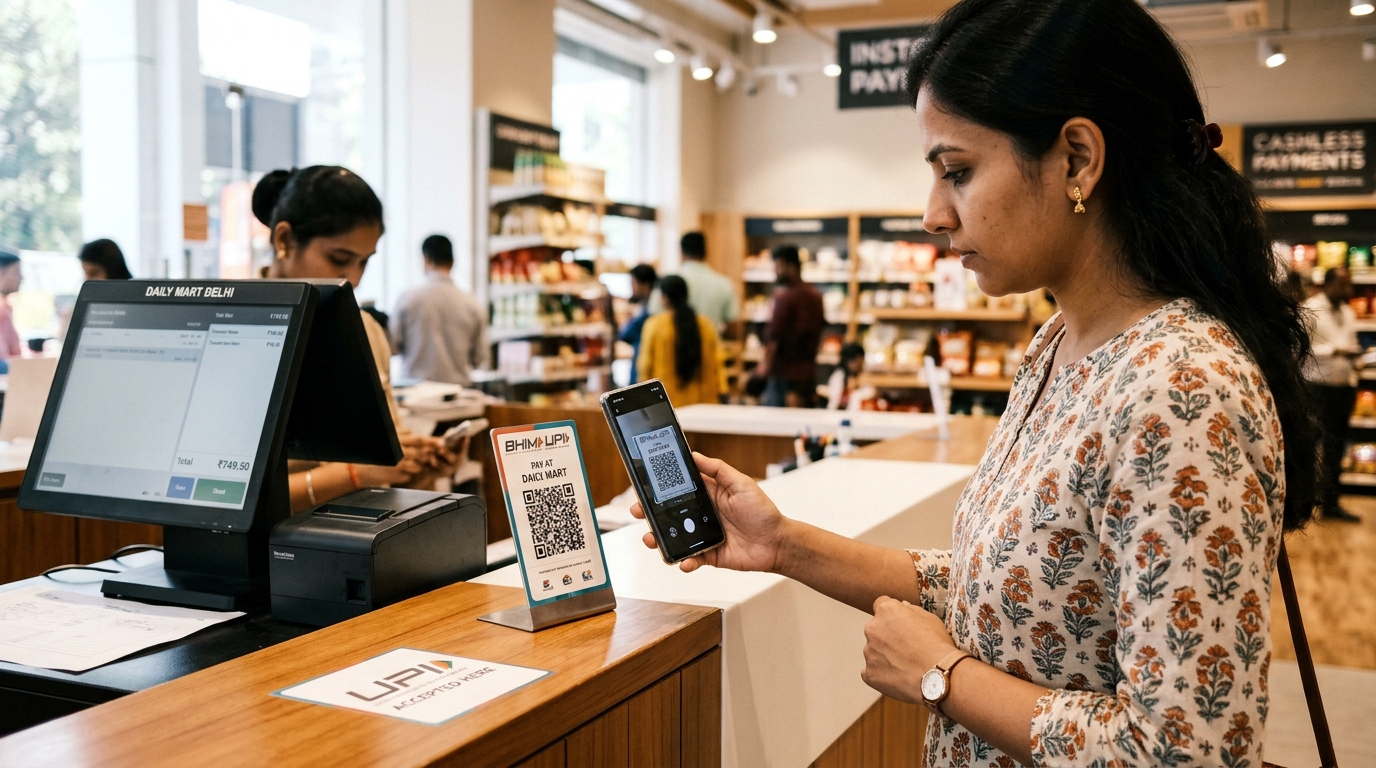
The intersection of India's Digital Public Infrastructure (DPI) with sovereign retirement architecture has triggered a quiet revolution in voluntary household wealth accumulation. Guided by the Pension Fund Regulatory and Development Authority (PFRDA) and enabled by modern Central Recordkeeping Agencies (CRAs), the migration of the National Pension System (NPS) into an entirely digital, API-driven framework has expanded pension coverage to over 40 million non-government subscribers.
1. The End of Bureaucratic Onboarding: Instant PRAN via Aadhaar and DigiLocker
Historically, opening a Permanent Retirement Account Number (PRAN) required physical forms, wet signatures, in-person verification at designated Points of Presence (POPs), and processing lead times extending to 21 days. Today, the e-NPS digital pipeline leverages Aadhaar e-KYC and DigiLocker integrations to verify identity, address, and bank mandates autonomously within three minutes.
By eliminating physical paper handling, onboarding distribution costs collapsed from upwards of ₹350 per registration to under ₹15. This structural cost compression allowed fintech aggregators and digital wealth platforms to offer zero-commission pension onboarding, making retirement accumulation accessible to micro-entrepreneurs and gig workers across Tier-2 and Tier-3 India.
— Dr. Deepak Mohanty, Former Chairman, PFRDA
2. Algorithmic Asset Allocation and the 0.09% Expense Ratio Advantage
The core economic appeal of digital NPS Tier-I and Tier-II accounts lies in their institutional fund management fee structure. While commercial retail mutual funds often charge expense ratios between 1.0% and 2.2%, PFRDA-regulated pension fund managers (including SBI Pension Funds, HDFC Pension, and ICICI Prudential Pension) operate under capped management fees of just 0.09%.
Over a 30-year accumulation horizon, a 150-basis-point difference in management fees generates a staggering 38% higher terminal retirement corpus for the saver. Subscribers utilizing automated Auto-Choice Lifecycle Funds (LC75, LC50, LC25) benefit from algorithmic risk de-risking: equity exposure automatically tapers by 2.5% annually starting at age 35, shifting capital into central government securities and corporate debt as retirement approaches.
3. Comparative Matrix: Legacy Pension vs. Digital e-NPS 2.0
The following performance audit illustrates the technological leap achieved across the National Pension System:
| Operational Parameter | Legacy Manual NPS (Pre-Digital) | Current e-NPS 2.0 (DPI Integrated) | Efficiency Factor |
|---|---|---|---|
| PRAN Generation Timeline | 14 to 21 business days | Under 3 minutes (Paperless) | 99.9% speed acceleration |
| Contribution Processing | T+4 banking days | T+1 instant NAV realization via UPI | Near-instant settlement |
| Fund Management Charges | 0.25% - 0.50% | 0.09% (World's lowest cost) | Institutional fee parity |
| Micro-Contribution Floor | ₹1,000 lump-sum minimum | ₹50 via UPI recurring mandate | Inclusive micro-savings |
| Corporate Tier-II Integration | Manual HR payroll filing | Automated API-driven payroll deductions | Zero employer compliance drag |
4. The Role of UPI AutoPay and Central Recordkeeping Agencies (CRAs)
The catalytic catalyst for retail participation has been the integration of the National Payments Corporation of India (NPCI) UPI AutoPay recurring mandate framework with the three central CRAs (Protean eGov, KFintech, and CAMS). Self-employed professionals, freelance software developers, and delivery fleet contractors can now establish daily or weekly micro-SIPs of ₹100 directly into their NPS Tier-I accounts.
These micro-debits are aggregated daily and deployed into high-yield sovereign paper and Nifty 50 index portfolios without incurring transaction friction. The behavioral outcome has been dramatic: subscriber persistence rates have surged from 48% under annual contribution reminders to over 89% under automated micro-SIPs.
Total assets under management (AUM) governed by PFRDA have expanded from ₹5.8 lakh crore in 2021 to over ₹14.2 lakh crore in 2026, with voluntary private sector registrations outpacing mandatory government enrollments for the first time in program history.
5. Looking Forward: Account Aggregators and Instant Annuity Portability
The next frontier of pension fintech in India involves the Account Aggregator (AA) framework. By linking their PRAN with certified Financial Information Users (FIUs), citizens can now aggregate their bank balances, mutual fund portfolios, EPFO balances, and NPS retirement wealth onto a single cryptographically secure dashboard.
Furthermore, PFRDA's upcoming instant digital annuity portability protocol will allow retiring subscribers to compare and bind lifelong pension annuities across 15 insurance providers via open competitive bidding, boosting final annuity yields by an estimated 45 to 65 basis points. Through open standards, algorithmic governance, and sovereign trust, India's pension technology sets a global benchmark for digital financial inclusion.